





10Life Financial Limited
Enquiries: enquiries@10life.com
Hotline: (852) 3705 1599
Address: 16/F Greatmany Centre, 109-115 Queen’s Road East, Wan Chai, Hong Kong


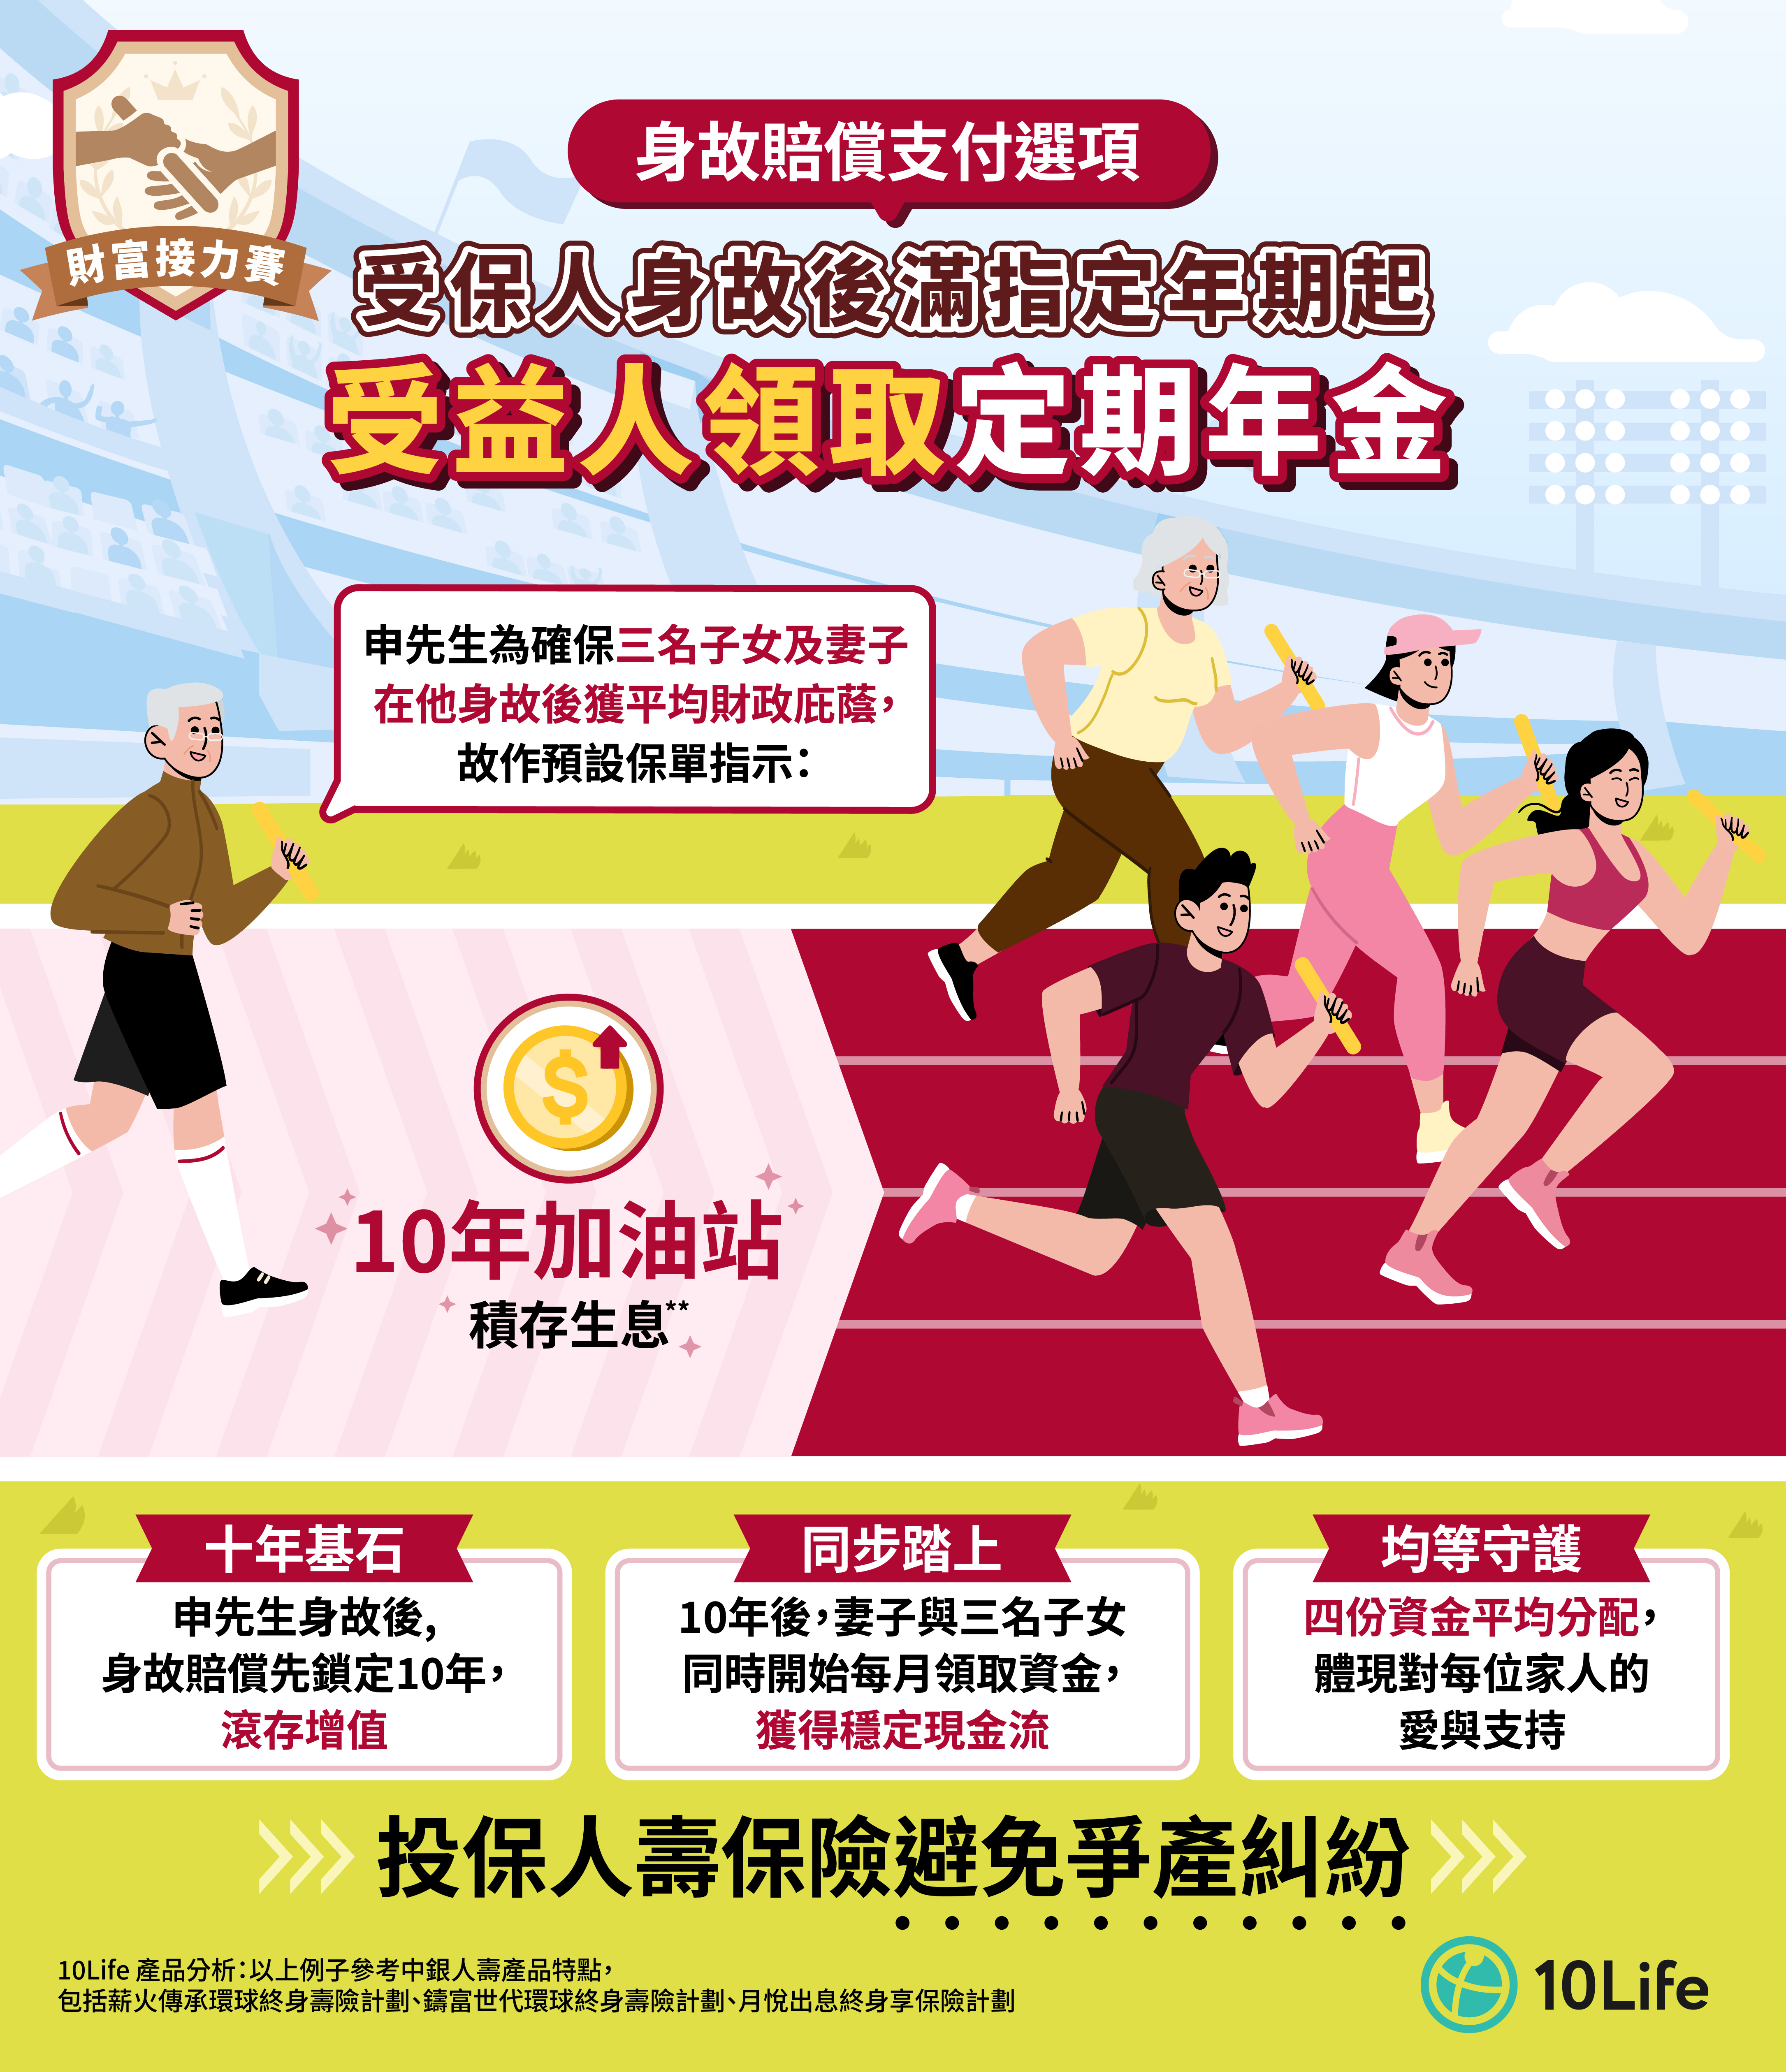
Succession Element 1: Death Benefit Payment Options
Succession planning element two: contingent insured person / second policy owner
Handover Element 3: Change of Insured Person
Handover Element Four: Contingent Beneficiary
Handover Factor Five: Currency Conversion
Succession Planning Element Six: Policy Splitting
Life insurance incorporating six key legacy-planning elements


For many middle-class families, wealth succession is a relay race through life. Growing the assets accumulated through years of hard work and successfully passing this love and wealth on to the next generation is an important life lesson.
However, unlike the ultra-wealthy, who have family offices or dedicated legal teams, middle-class families can easily fall into a misconception in the absence of professional support: believing that simply leaving behind cash or property is enough to pass the baton in this wealth relay race. Such an approach not only overlooks the market risks associated with excessive asset concentration, but also fails to take into account the tax and legal costs involved in the transfer process. Should family disputes arise over the distribution of assets, they could not only damage family relationships, but potentially destroy a lifetime’s hard work. Middle-class families therefore have an absolute need for comprehensive succession planning.
Traditionally, when planning for wealth succession, people generally consider making a will or establishing a trust. However, both have significant limitations: a will is inflexible and offers no potential for asset growth, making it unable to adapt flexibly to future changes; trusts involve high entry thresholds and ongoing management fees, as well as complicated procedures, and may not be suitable for middle-class families. By comparison, a comprehensive life insurance policy can help the policyholder run faster and further in the wealth relay race, while enabling the baton to be passed smoothly to the next “runner”. To ensure that life insurance can genuinely fulfil this role, the key lies in whether it incorporates the following six elements for passing on the baton:
Succession Element 1: Death Benefit Payment Options
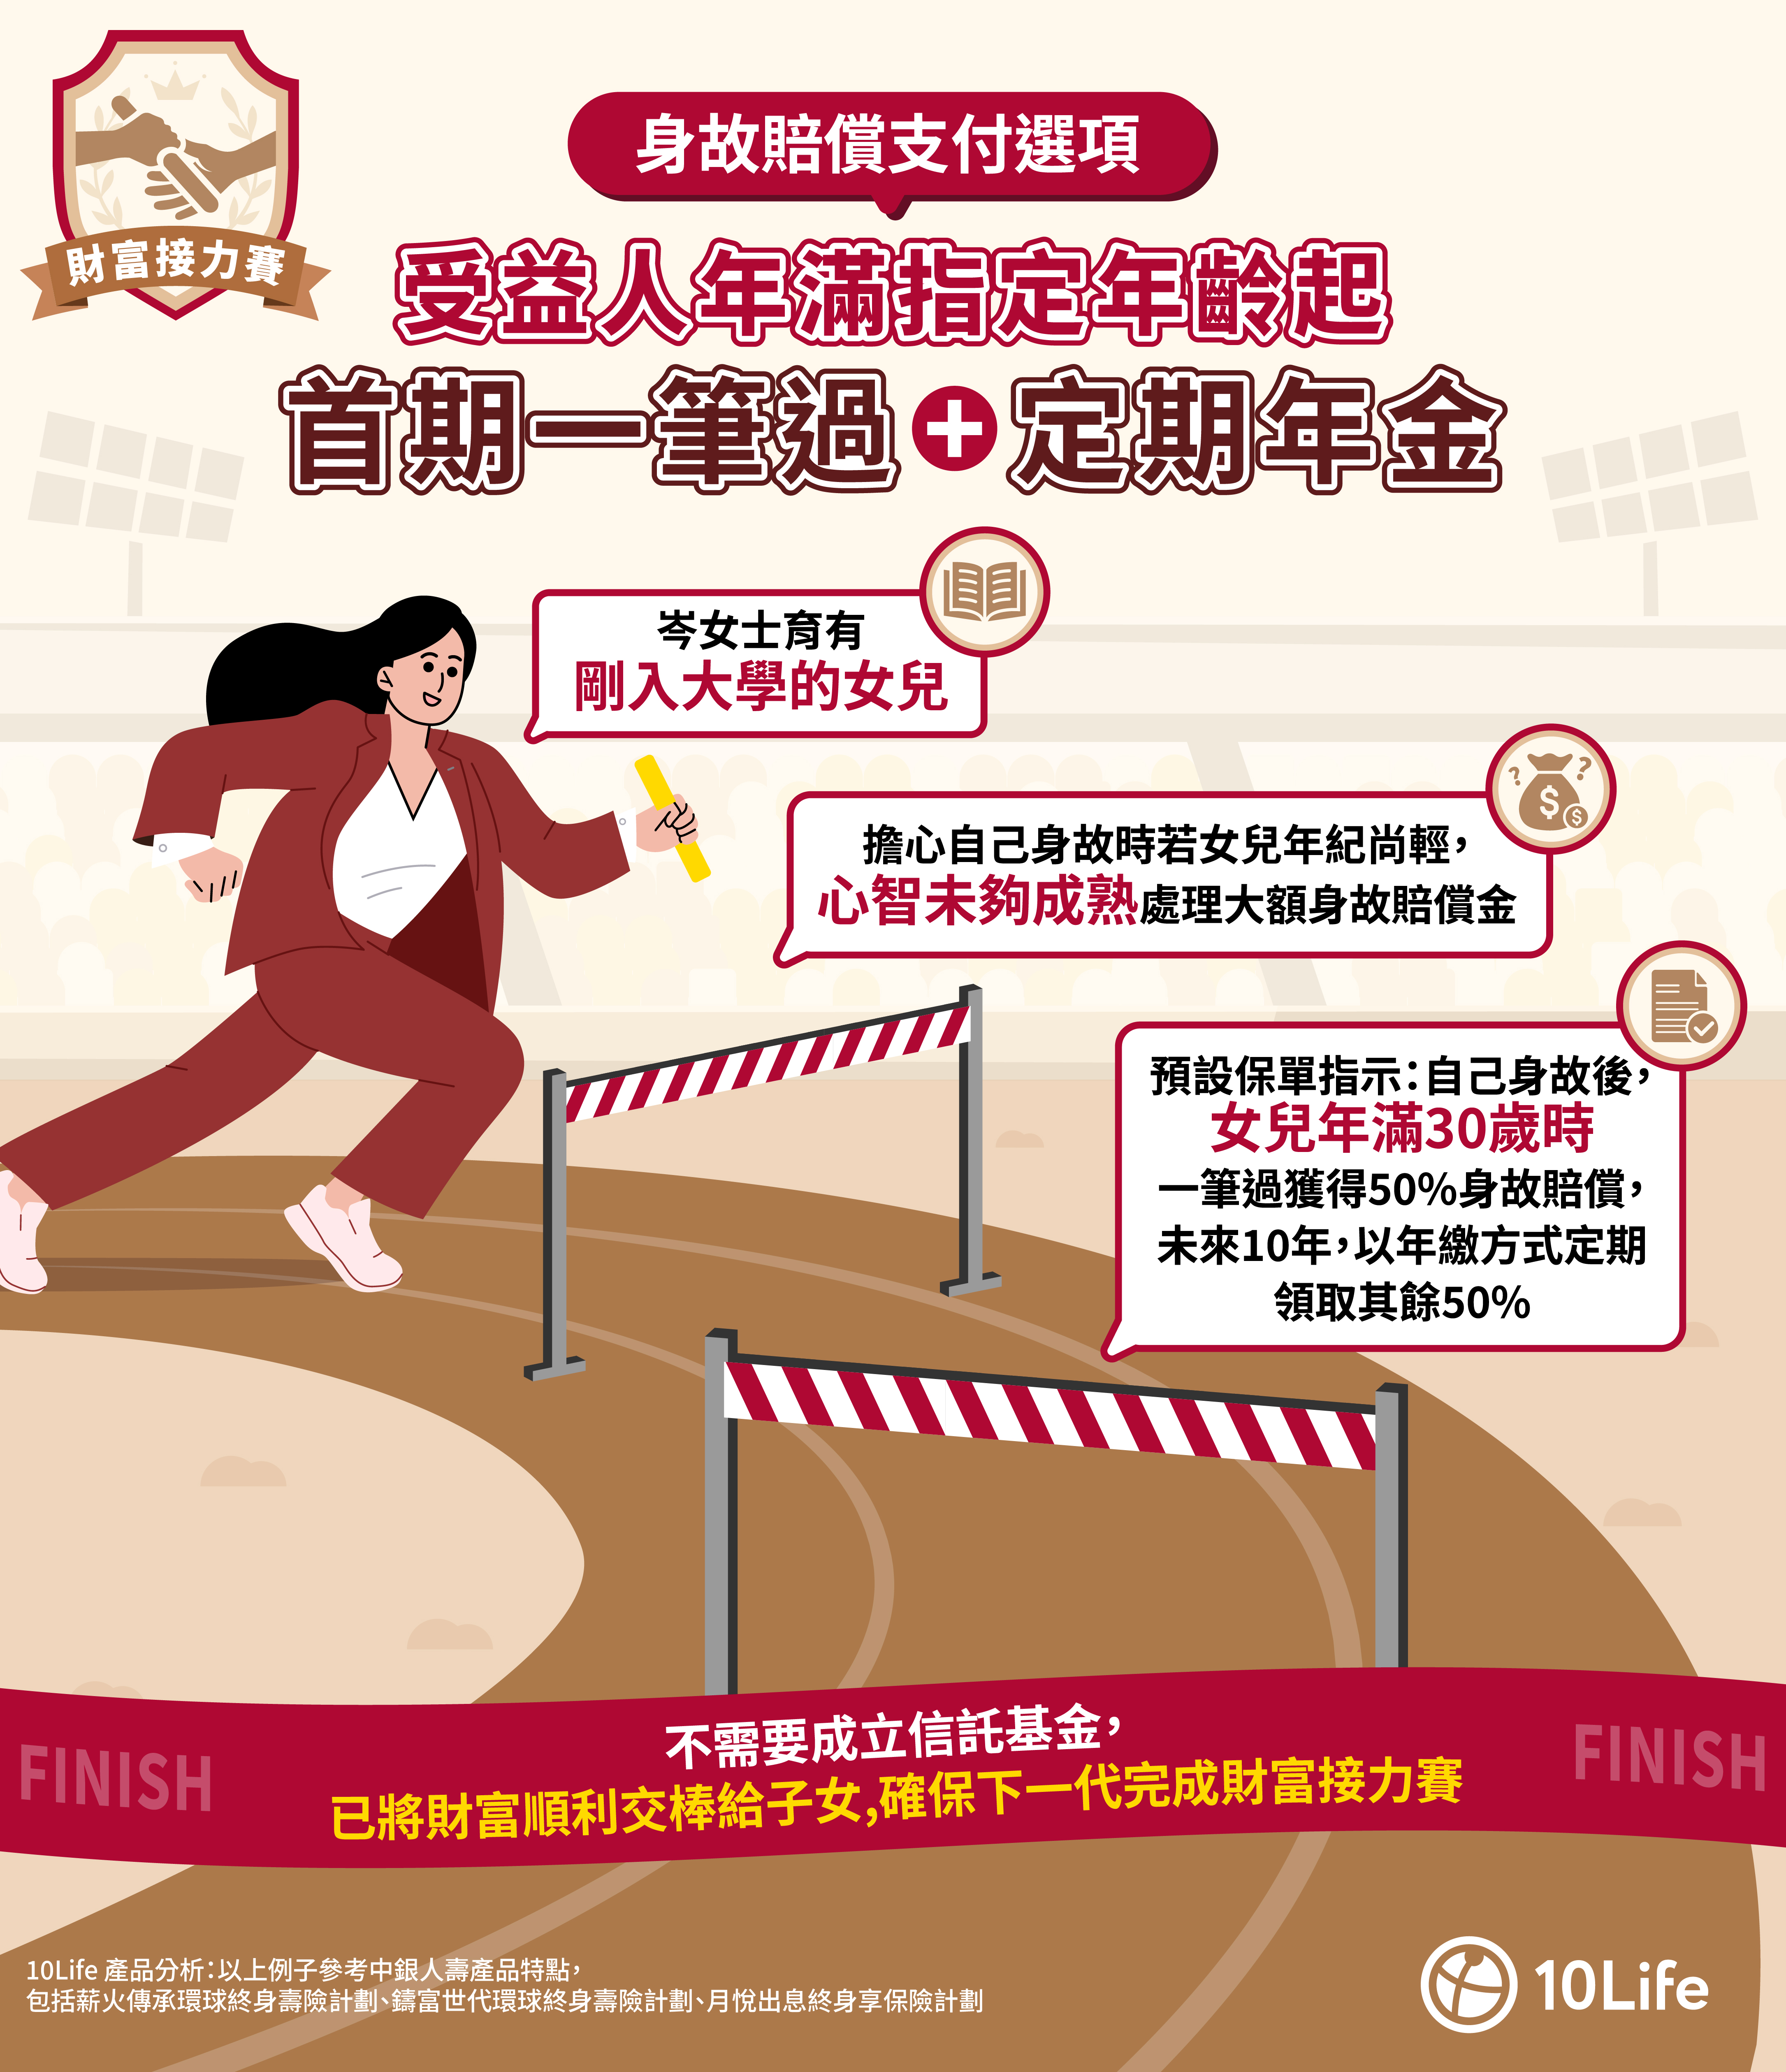
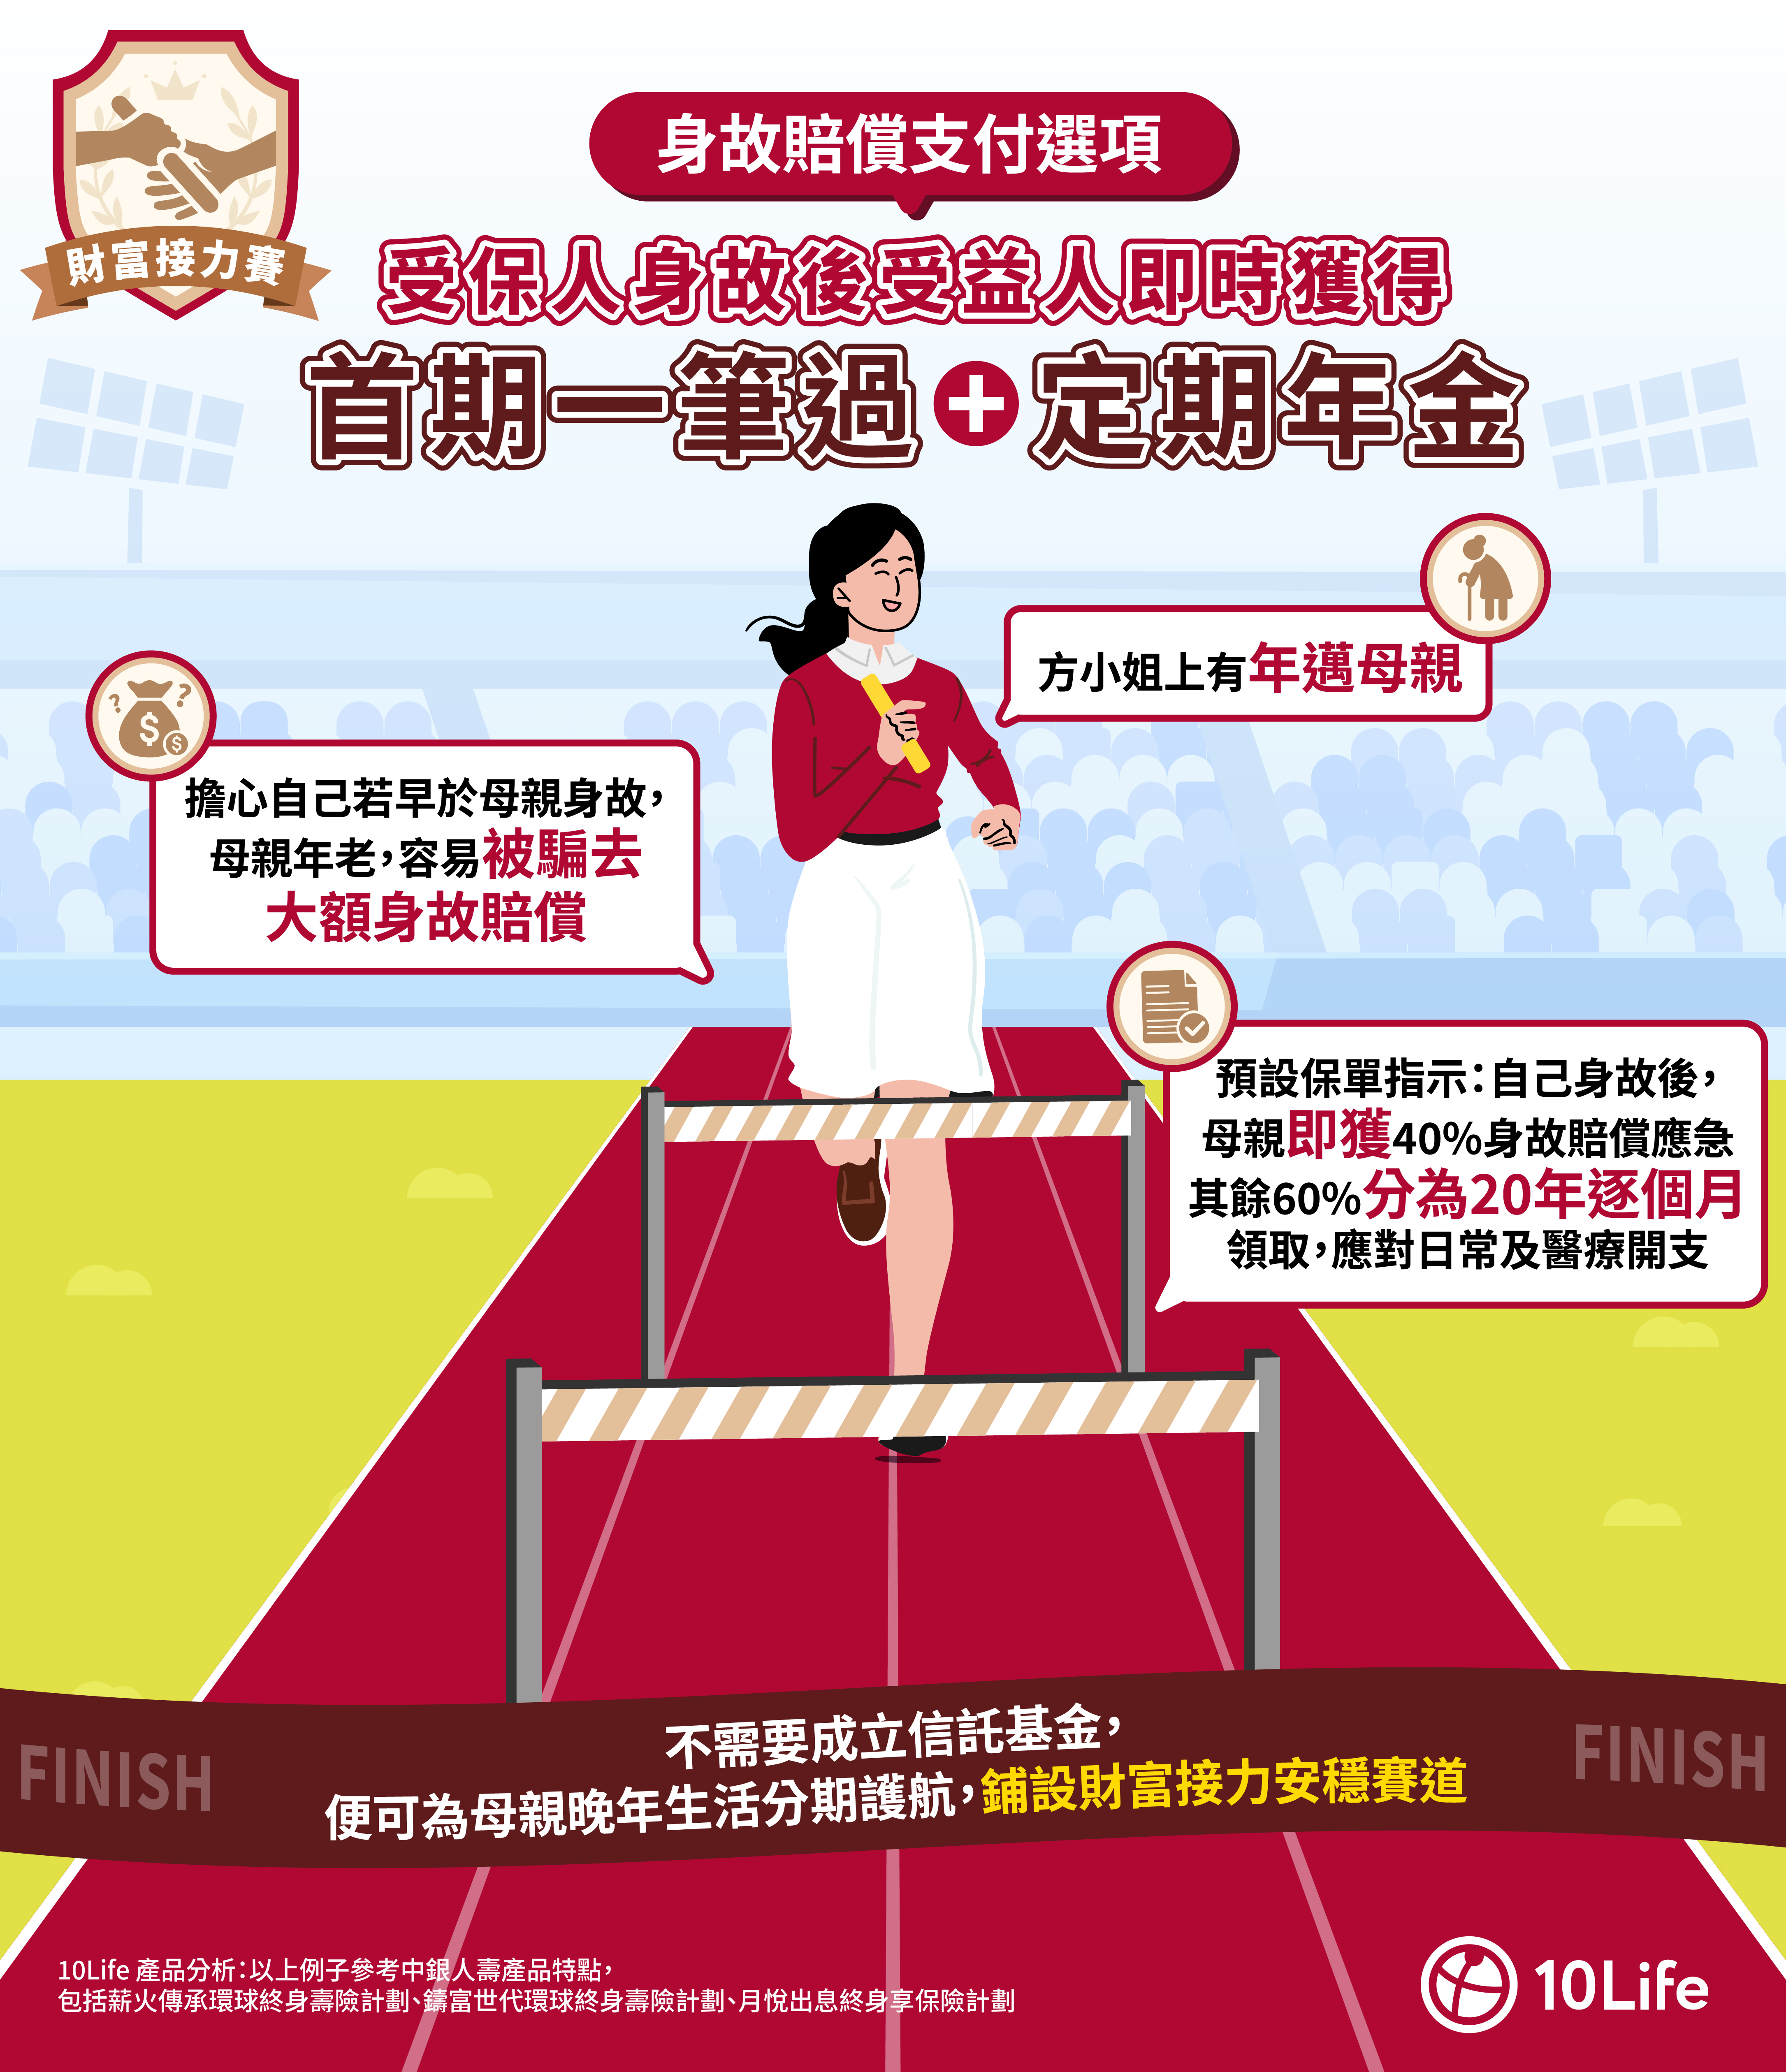
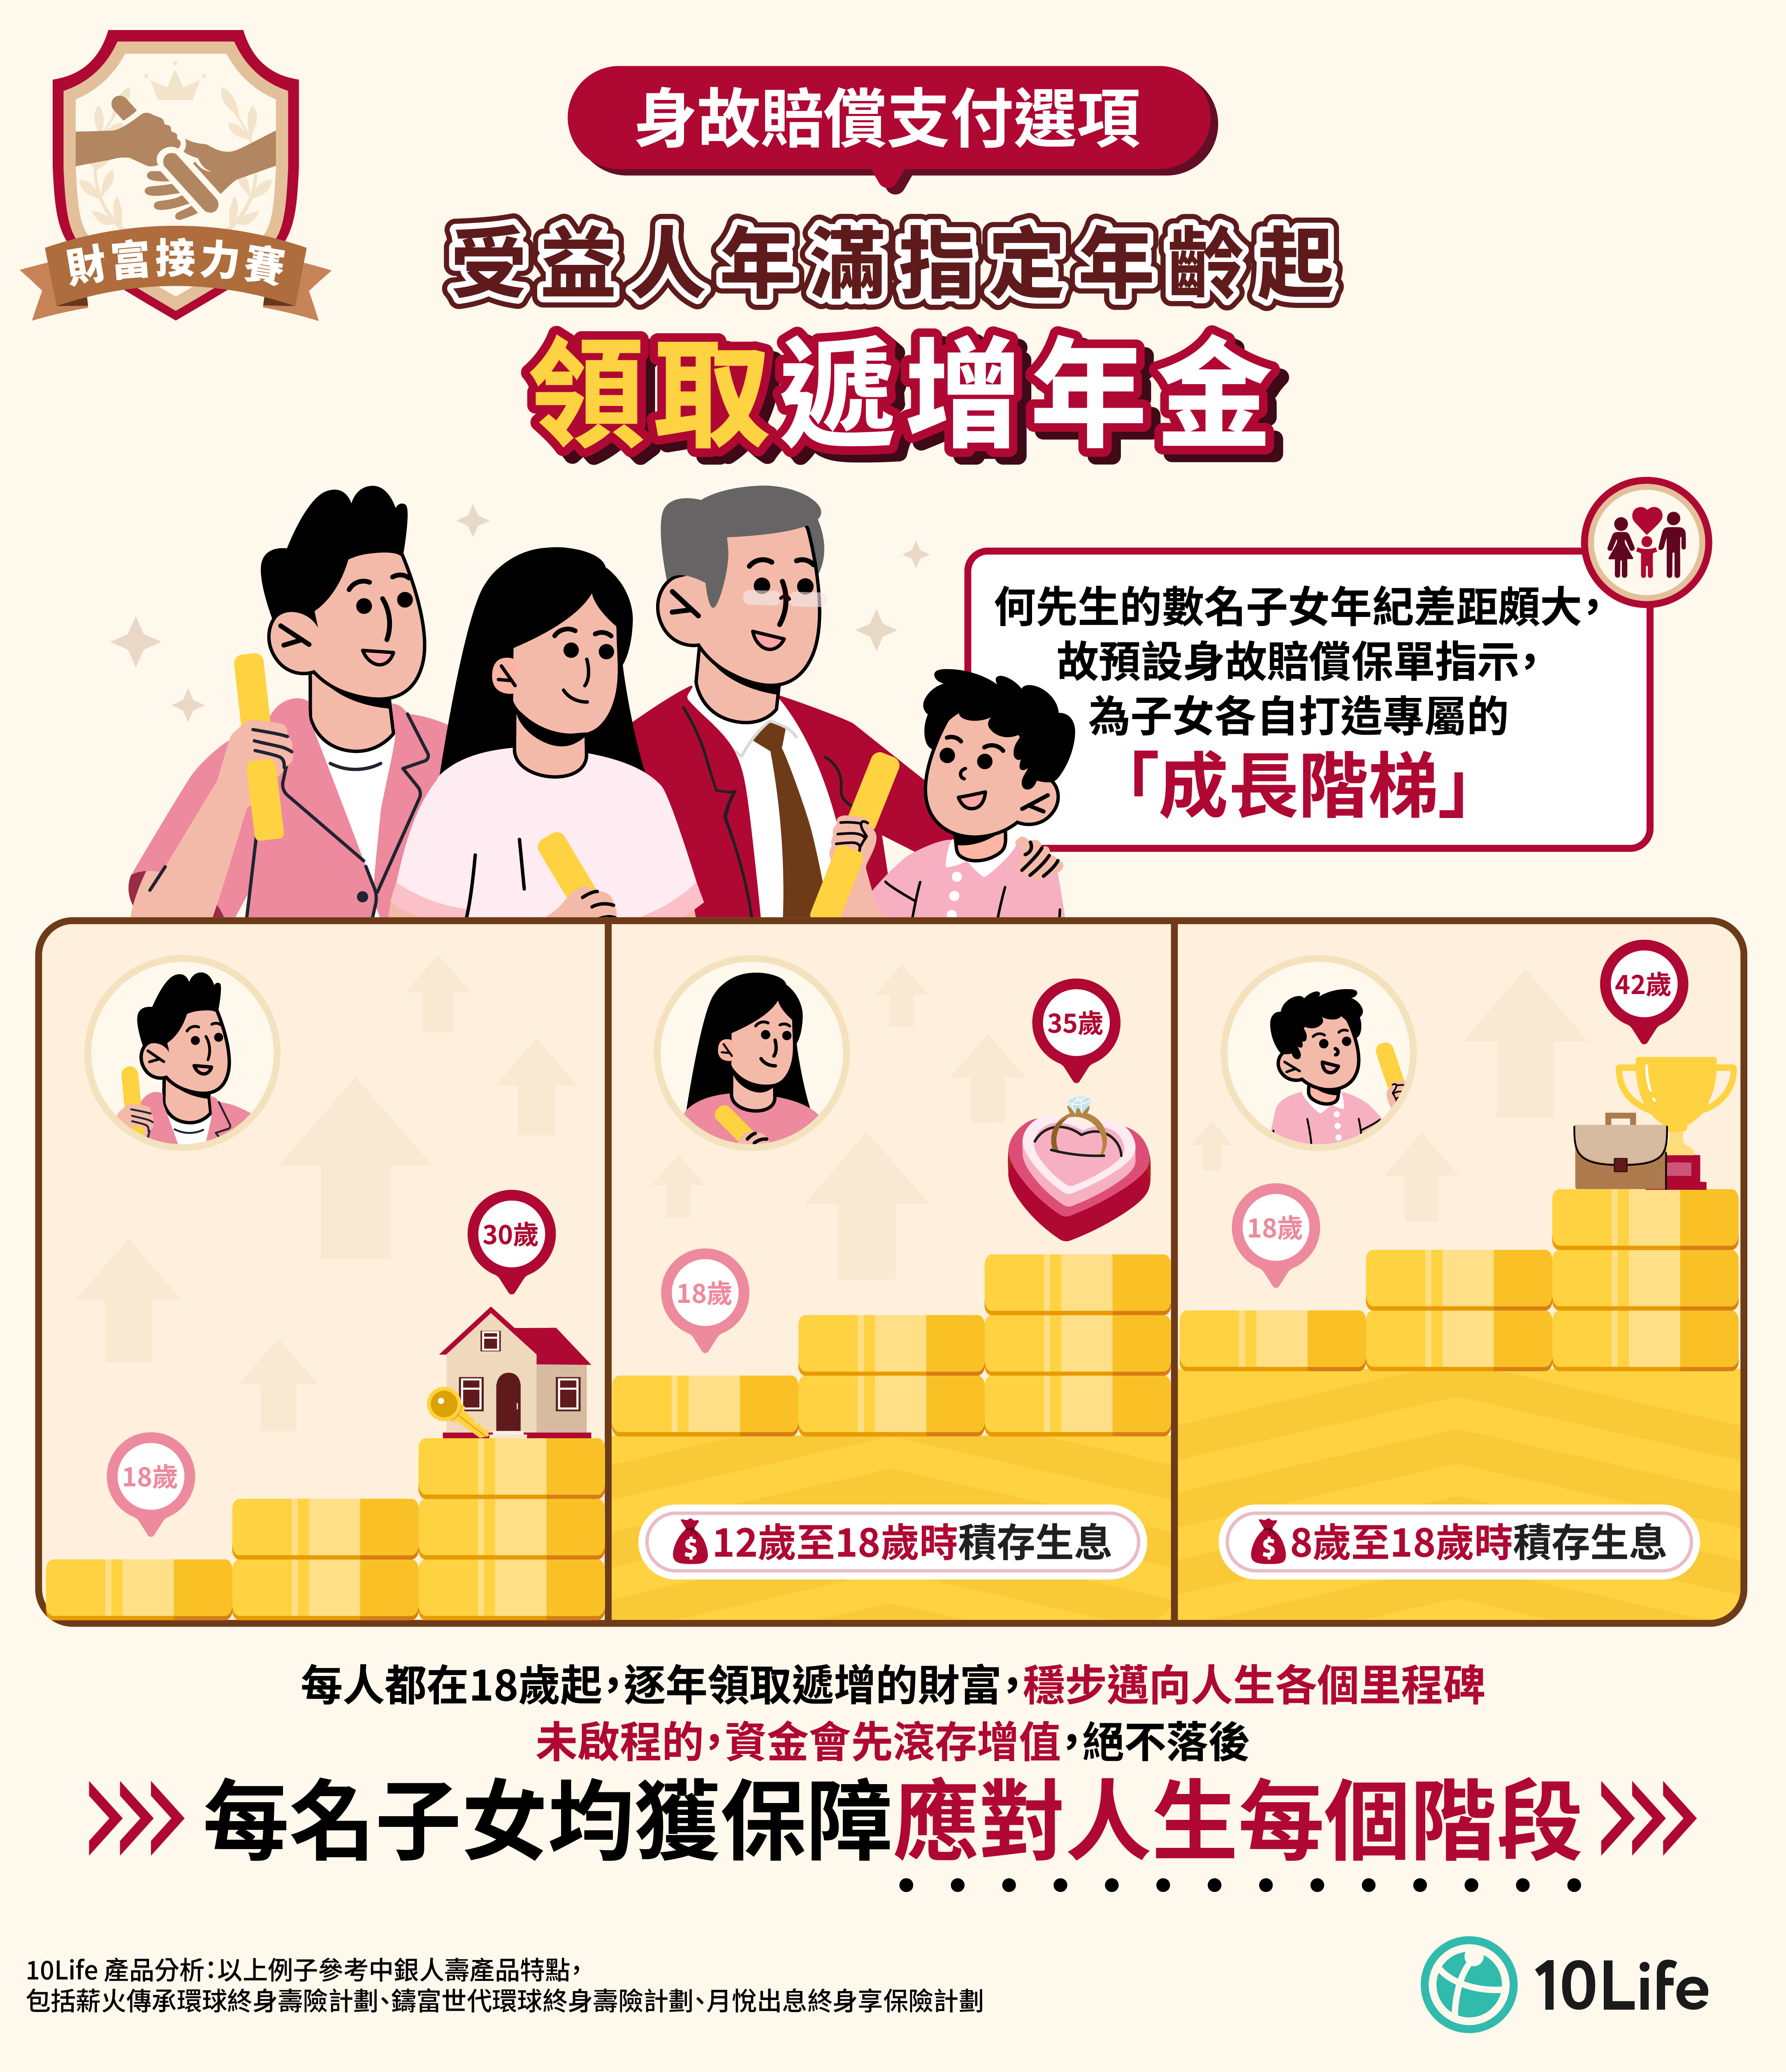
When parents pass their wealth on to their children, their greatest concern is often that their children may be unable to make good use of the assets due to their limited experience. The “death benefit payment options” in life insurance can address this concern, allowing policyholders to determine in advance the length of the track for this wealth relay by setting how the death benefit is to be paid.
Policyholders can decide whether the beneficiaries receive the death benefit immediately, or only when they reach a specified age or after a specified number of years following the policyholder’s death; they can also choose from flexible payment methods, such as a single lump-sum payment, payment in instalments as an annuity, or even a combination of these options. Even when parents are no longer present, their wealth can still be transformed according to their wishes into a long-term blessing, rather than a substantial sum that may be squandered.
Succession planning element two: contingent insured person / second policy owner
Think of a legacy policy as a wealth relay race, where the greatest fear is that the baton will be dropped midway and the race brought to an end. The “backup insured” is the “second runner” appointed for this purpose. When the original insured passes away, they take over seamlessly, allowing the policy’s value to continue growing and ensuring that the race goes on.
The “second policy beneficiary” is like an “accompanying coach”. Their responsibility is to manage the policy after the policy beneficiary (that is, the policyholder) passes away. If the child taking over the baton is still a minor, they manage the policy on the child’s behalf until the child is able to take the helm independently, safeguarding a smooth and secure transfer of wealth.
Handover Element 3: Change of Insured Person
If policy value growth is likened to an infinitely extending relay race, the life span of the insured determines the length of the current leg. The “Change of Insured” feature allows the policyholder, during their lifetime, to pass the “runner’s” identity on to a younger generation. This is like seamlessly extending the track into the future, enabling the policy to continue accumulating value and allowing the baton to be passed to an unlimited number of generations of “runners”, thereby achieving the perpetual transfer of wealth.
Handover Element Four: Contingent Beneficiary
A wealth relay is intended to ensure that wealth is accurately passed on to the designated person. However, life is unpredictable. If the first beneficiary of the policy unfortunately dies before the policyholder, and the policyholder fails to designate another beneficiary in time; or, in extreme circumstances, if the policyholder and the first beneficiary die at the same time, the proceeds may not be smoothly passed on to the intended family member.
The role of a “second beneficiary” is that, when the death benefit cannot be passed on to the first beneficiary of the policy due to the circumstances above, it will instead be received by the designated second beneficiary. This helps avoid the insurance proceeds being drawn into lengthy legal proceedings or failing to be distributed as originally intended due to disputes. This arrangement is equivalent to taking out “double insurance” for the inheritance plan, ensuring that the policyholder’s carefully planned blessing is delivered accurately and without error to the ultimately designated person.
Handover Factor Five: Currency Conversion
The race to pass on wealth spans the globe. If the currency allocation of assets does not align with the needs of the next generation, the value of the inheritance may be diminished by exchange-rate fluctuations and conversion costs.
The “Currency Conversion” feature allows policyholders, after a specified term, to convert their policy into the local currency—such as pounds sterling, Australian dollars or Canadian dollars—in response to their actual needs, including their place of residence at the time, such as the UK, Australia or Canada. This design ensures that, wherever they are striving to build their lives, these funds from their family can serve as an important source of support.
Succession Planning Element Six: Policy Splitting
When there are multiple children, it can be difficult to pass on a single policy flexibly. The “Policy Splitting” feature allows one master policy to be split into multiple policies, creating several independent “batons” to be handed to each child. This is not merely a simple distribution of assets, but provides each child with dedicated start-up capital that can be used flexibly for personalised goals such as starting a business or pursuing further education, transforming one blessing into multiple forms of targeted support.
Life insurance incorporating six key legacy-planning elements
Taking all six key elements together, a truly effective wealth succession tool needs to do more than offer a single function; it must integrate them into a complete solution that is both flexible and secure. Few products on the market comprehensively combine all these features. BOC Life’s life insurance products1 are designed on this basis, with the aim of providing middle-class families with a one-stop solution that thoughtfully addresses every detail, from wealth growth to intergenerational succession. This helps policyholders achieve worry-free wealth planning and smoothly pass on their wealth to the next generation, and even to generations beyond.
Notes:
1. The above examples refer to the features of BOC Life products, including Glamorous Glow Global Whole Life Insurance Plan, Eternal Fortune Global Whole Life Insurance Plan and IncomeJoy Lifelong Insurance Plan
2. Last updated: 26 September 2025
This English version of this article has been generated by machine translation powered by AI. It is provided solely for reference purposes. In the event of any discrepancy or inconsistency between this translation and the original Chinese version, the Chinese version shall prevail.
Our team of professional content researchers focussing on insurance
Our team of professional content researchers focussing on insurance
10Life Product Comparison and 10Life Insurance Ratings are developed by 10Life Financial Limited, an authorised insurance broker company licensed with the Insurance Authority under License Number FB1526. 10Life Product Comparison and 10Life Insurance Ratings are developed for generic customer segments using mathematical calculations based on product information, facts and data, and are not influenced by any partnerships with or fees received from insurance companies. Any information on 10Life Platform ("10Life Information"), including but not limited to Product Comparison, Product Ratings, Blog Articles are intended for general education purpose and reference only. None of the 10Life Information is intended, nor should they be considered or relied upon, as regulated advice, insurance, financial, investment or professional advice, recommendation, approval, endorsement, invitation or solicitation in respect of any insurance, financial or investment products. 10Life Information does not take into account your individual needs. Reading 10Life Information should not be considered as conducting a suitability assessment, and is not sufficient to form the basis of any decisions to purchase any insurance products. You should rely on information authorised by insurance companies, carry out your own research and/or seek independent advice from licensed intermediaries before purchasing any insurance products or making any insurance decisions. While reasonable effort is used when collecting, validating and updating 10Life Information from various channels, none of 10Life Group and its subsidiaries, affiliates, agents, directors, officers and employees will be responsible for any liability, claim or loss arising from or associated with you using 10Life Information. No warranty, representation or guarantee is given by 10Life Group and its subsidiaries on the accuracy, completeness and timeliness of the information. If you have any questions on 10Life Product Comparison and 10Life Insurance Ratings, please email us at enquiries@10life.com


 Talk to 10Life on WeChat
